Real cost ranges by policy type. We compare 30+ A-rated carriers so you can see the range.
Last reviewed September 2026 by Dev Gaymes, Texas-licensed life insurance agent, NPN 16654074 · Editorial policy
We're independent. We don't set prices. The carriers do. Our job is to shop 30+ of them and show you what each will do with your file. Ranges below are typical for healthy applicants.
Life insurance pricing is less mysterious than it looks. Six things drive almost all of it, roughly in order of impact:
Most pages on this topic give ranges. Here are actual numbers - 20-year level term, Preferred rate class, non-tobacco, pulled September 2026 for a Texas applicant. Preferred is a healthy-applicant class - if you would price at Standard or below, expect meaningfully higher figures.
Sample monthly premiums pulled September 2026 for a Texas applicant, representative of rates available across appointed A-rated carriers. Illustrative only - not a quote, not an offer of insurance, and not a guarantee of eligibility. Your premium depends on age, health, tobacco status, coverage amount, product and the carrier that underwrites your file. All coverage is subject to underwriting approval. Preferred class - a healthy applicant with good build, blood pressure and labs. An ordinary Standard profile prices above these; see the rate class table on our health conditions page for the spread.
Same man, same $500,000 twenty-year policy, Preferred non-tobacco throughout. Only the age at purchase changes.
Sample rates pulled September 2026, Texas, Preferred non-tobacco. Illustrative only, not a quote.
Two people the same age buying the same policy can pay very different premiums because they were assigned different rate classes. Carriers use their own names, but the tiers generally run:
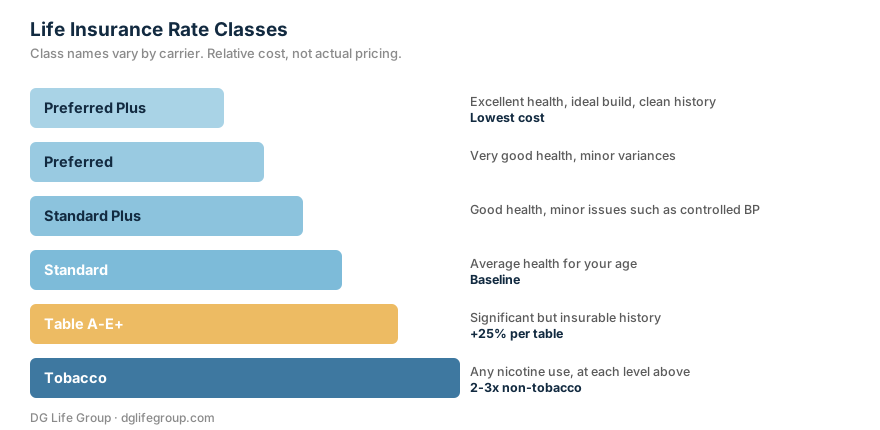
Class names and criteria vary by carrier and are applied at the underwriter's discretion. This is a general map, not any insurer's guidelines.
This is the part that surprises people, and it is the reason independent brokerage exists.
Rates are filed with state regulators. A given carrier's premium for a given person is the same whether you buy directly from them, through a call center, or through a broker. Nobody has a secret discount.
What differs is which carrier evaluates your file. Each one prices according to its own claims experience, so the same applicant can be Preferred at one company and table-rated at another. Industry analysis in 2026 found premiums for identical coverage commonly varying 5 to 20 percent between top carriers. And that spread widens sharply once any health history is involved.
Accurate pricing needs accurate inputs. For a straightforward case: date of birth, height and weight, tobacco or nicotine use of any kind, current medications and conditions, and a rough idea of coverage amount and term.
For larger policies, financial underwriting adds tax returns or a net worth statement, because carriers cap coverage at an age-based multiple of income.
$5K–$50K whole life for end-of-life costs. Simplified underwriting, guaranteed issue. Rates vary by age and health.
Decisions often in minutes. Health questionnaires + database checks. Rates can match full underwriting for healthy applicants, though a strong medical file can sometimes earn a better class with an exam. Try it now →
Illustrative numbers only go so far. A 15-minute call gets you real, shopped quotes.
Prefer to talk now? Call 214-989-7704
Rate disclosure. Premiums shown are illustrative estimates for healthy non-smokers and are not a quote or an offer of coverage. Actual premiums depend on age, health, tobacco use, coverage amount, term length, state, carrier, and underwriting approval. Rates and product availability vary by carrier and by state.
Age sets the starting point; your underwriting class moves it most. Here is one policy for a 45-year-old man, $500,000 of 20-year term, non-tobacco, priced at each class.
Sample monthly premiums quoted September 2026 for a Texas applicant, from one carrier’s rate ladder; other carriers’ ladders differ. Illustrative only, not a quote or an offer of insurance. Why online quotes often show the top class.
At Preferred non-tobacco rates quoted in Texas in September 2026, $500,000 of 20-year term was about $34.64 a month for a 40-year-old man and $28.73 for a 40-year-old woman (illustrative, not a quote). Rates are filed with the Texas Department of Insurance, so they do not vary by Dallas neighborhood. Your health class is what moves the price.
At Preferred non-tobacco rates quoted in Texas in September 2026, $500,000 of 20-year term was about $24.92 a month for a 35-year-old man, $34.64 at 40, $53.23 at 45 and $82.62 at 50 (illustrative, not a quote). Women's rates run lower. Your health class moves the price most, and the premium is locked for the full term.
At Preferred non-tobacco rates quoted in Texas in September 2026, $500,000 of whole life was about $530.86 a month for a 35-year-old man and $785.93 at 45 (illustrative, not a quote). Premiums are fixed for life and build guaranteed cash value. Some carriers also pay dividends, which are not guaranteed. Whole life costs far more than term for the same death benefit, in exchange for coverage that does not expire.
Yes. No-medical-exam policies use health questionnaires and electronic database checks. Many clients are approved in minutes. Rates are often the same or similar to fully underwritten policies. DG Life Group offers instant term life quotes through their online quoting tool.
DG Life Group is paid by the insurance carrier when a policy is placed, so there is no fee to you. Rates are filed with state regulators, so the premium is the same whether you buy through us or directly. Commissions do vary by carrier and product, and we will tell you ours on any policy we show you.